How to prepare a Baltic company for sale: the twelve-month checklist
What to fix, document and decide before you go to market — the preparation that raises a sale price and keeps a deal from collapsing in due diligence.
The best time to prepare a company for sale is about two years before you want to sell it. The second-best time is now. Most of what raises a sale price — and most of what makes a sale complete rather than collapse in diligence — is not clever negotiation on the day. It is unglamorous preparation done well in advance, so that when a buyer looks closely there is nothing to find that they did not already know. This is the checklist we would give any owner of a small or mid-sized company in Estonia, Latvia or Lithuania who is thinking about an exit.
Twelve months or more before: fix the fundamentals
Get the accounts clean and current. Three years of accounts that reconcile to the bank, to the tax authority and to the public registry are the foundation of everything. If your management accounts and your filed statements tell different stories, resolve that now — buyers assume the less favourable version is true.
Separate the business from yourself. Take personal expenses out of the company. Put family members' roles on a proper footing or move them off the payroll. If you rent premises to your own company, put a market-rate lease in writing. Every related-party arrangement is a diligence question, and every question costs time or price.
Reduce your own indispensability. Document how the business runs. Delegate customer relationships to a second person and let that person be seen by the customers. If you are the only one who can quote, price or sign, start changing that. A buyer who sees that the company runs when you are on holiday will pay more than one who sees that it stops.
Look at customer concentration. If one customer is a large share of revenue, a buyer will price the risk of losing them. You may not be able to change the mix in a year, but you can secure that customer on a longer contract, and you can show that you are actively winning others.
Deal with the skeletons. An unresolved dispute with a former employee, a lease that expires next year, a permit that lapsed, a shareholder who never signed the resolution — resolve them while you control the timetable. Nothing found in diligence is ever priced in your favour.
Six months before: assemble the story and the team
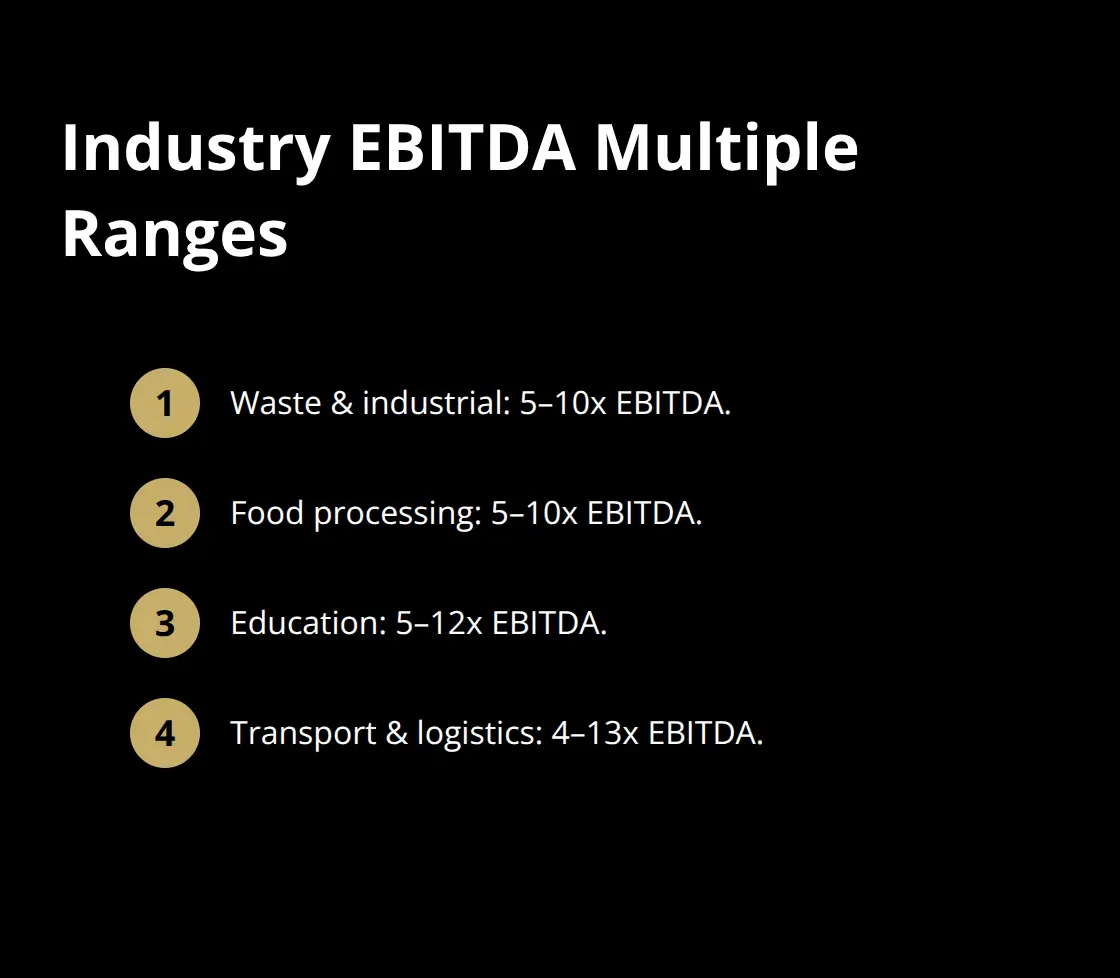
Understand your own valuation. Work out your normalised EBITDA — profit adjusted for owner remuneration, one-offs and related-party items — and be honest about which adjustments a sceptical buyer will accept. Our guide to how Baltic SMEs are valued explains the mechanics; the free valuation tool gives an indicative range.
Decide what you are selling. Shares or assets? The whole company or a majority stake? With the property or without? Each answer changes the buyer pool, the tax outcome and the price. Take advice on this early, because it shapes how the business is presented.
Choose your advisers. At minimum you will need a lawyer who does transactions (not just company secretarial work) and an accountant or tax adviser who can model the deal. Whether you use a broker or a marketplace depends on the size of the business and how much of the process you want to run yourself.
Prepare the information memorandum. This is the document that describes the business to a buyer who has signed a confidentiality agreement: history, market, customers, team, financials, the reason for sale, and what the future could look like under new ownership. Write it truthfully — every claim in it will be tested — but write it to sell.
Build a data room. A structured, complete set of documents ready before the first buyer asks for them: constitutional documents, share register, three years of accounts, tax filings, all material contracts, employment terms, leases, permits, insurance, IP registrations, and a list of assets. A well-organised data room shortens diligence by weeks and signals a well-run company.
Three months before: go to market
Decide who should not know. Confidentiality is the seller's main protection. Staff who hear a rumour start looking for other jobs; customers who hear one start looking for other suppliers; competitors who hear one start calling both. A teaser that describes the business without naming it, released only to buyers who have been screened and have signed an NDA, is how this is normally managed. Decide in advance which named competitors you will refuse to talk to at all.
Screen buyers before you meet them. A buyer's mandate, their funding and their track record are all reasonable things to ask about before you show them your company. Time spent with a buyer who cannot complete is time you do not get back.
Keep running the business. The most damaging thing a seller can do during a sale process is take their eye off performance. Buyers watch the current-year numbers closely, and a dip in the months before completion is the commonest reason for a price renegotiation.
During the process: negotiate the whole deal, not just the number
A headline price is only one term among many. The certainty of payment, how much is deferred or contingent on future performance, what warranties you give and for how long, whether you stay on and for how long, what you may and may not do afterwards — each of these has a value, and a buyer who moves on price will often want to recover it elsewhere. Know before you start which terms matter most to you.
Expect diligence to find things. If you have prepared well, they will be small and you will already have explained them. Respond quickly and completely; a seller who is slow to answer questions is assumed to be hiding something.
After completion: the handover
Most sales of owner-managed companies include a handover period in which the seller stays involved — weeks or months, sometimes longer with an earn-out. Plan it as carefully as the sale. Introduce the buyer to customers and suppliers personally. Transfer the relationships, not just the contracts. The buyer's success in the first year protects any deferred payment you are owed and, less tangibly, the reputation you spent years building.
The checklist in brief
- Clean, reconciled accounts for three years.
- Personal and related-party items removed or formalised.
- The business demonstrably runs without you.
- Key customers secured; concentration understood.
- Legal and regulatory loose ends tied up.
- Normalised EBITDA calculated and defensible.
- Deal perimeter decided: shares or assets, with or without property.
- Transaction lawyer and tax adviser engaged.
- Information memorandum and data room ready.
- Confidentiality plan, including buyers you will exclude.
- Buyer screening before any meeting.
- Business performance maintained throughout.
When you are ready, you can list your business as an anonymous teaser in all five of our languages, or talk to our team first about timing and approach.
This article is general guidance, not legal, tax or financial advice. Every sale depends on its own facts; take professional advice before acting.